Living Update
Buying vs. Renting a Condo: Which Should You Choose?
25 Sep 26

Buy vs Rent a Condo: What to Consider Before You Decide

“Should I buy a condo, or rent for now?” is one of the most common questions for anyone looking for a place to live. At the same time, there’s no single right answer that works for everyone—it depends on your life goals, lifestyle, and financial readiness.

Renting vs Buying a Condo: Key Differences at a Glance

Category Renting a Condo Buying a Condo (Mortgage)
Upfront cost Low (deposit + advance rent) High (down payment + transfer + mortgage fees)
Monthly cost Fixed rent per contract Mortgage instalment + common fees + utilities
Flexibility Very high, easy to move out Low, long-term commitment
Building an asset No ownership gained Builds ownership + potential capital gain
Freedom to decorate Fairly limited Full freedom
Repair responsibility Mainly the landlord’s responsibility The owner’s own responsibility


Is Buying a Condo on a Mortgage Better Than Renting?

Buy vs rent a condo

What Are the Benefits of Buying a Condo on a Mortgage?

Is buying a condo on a mortgage worth it? When you buy on a mortgage, every baht you pay builds ownership in an asset that’s yours—not just an expense that disappears. The key benefits include:
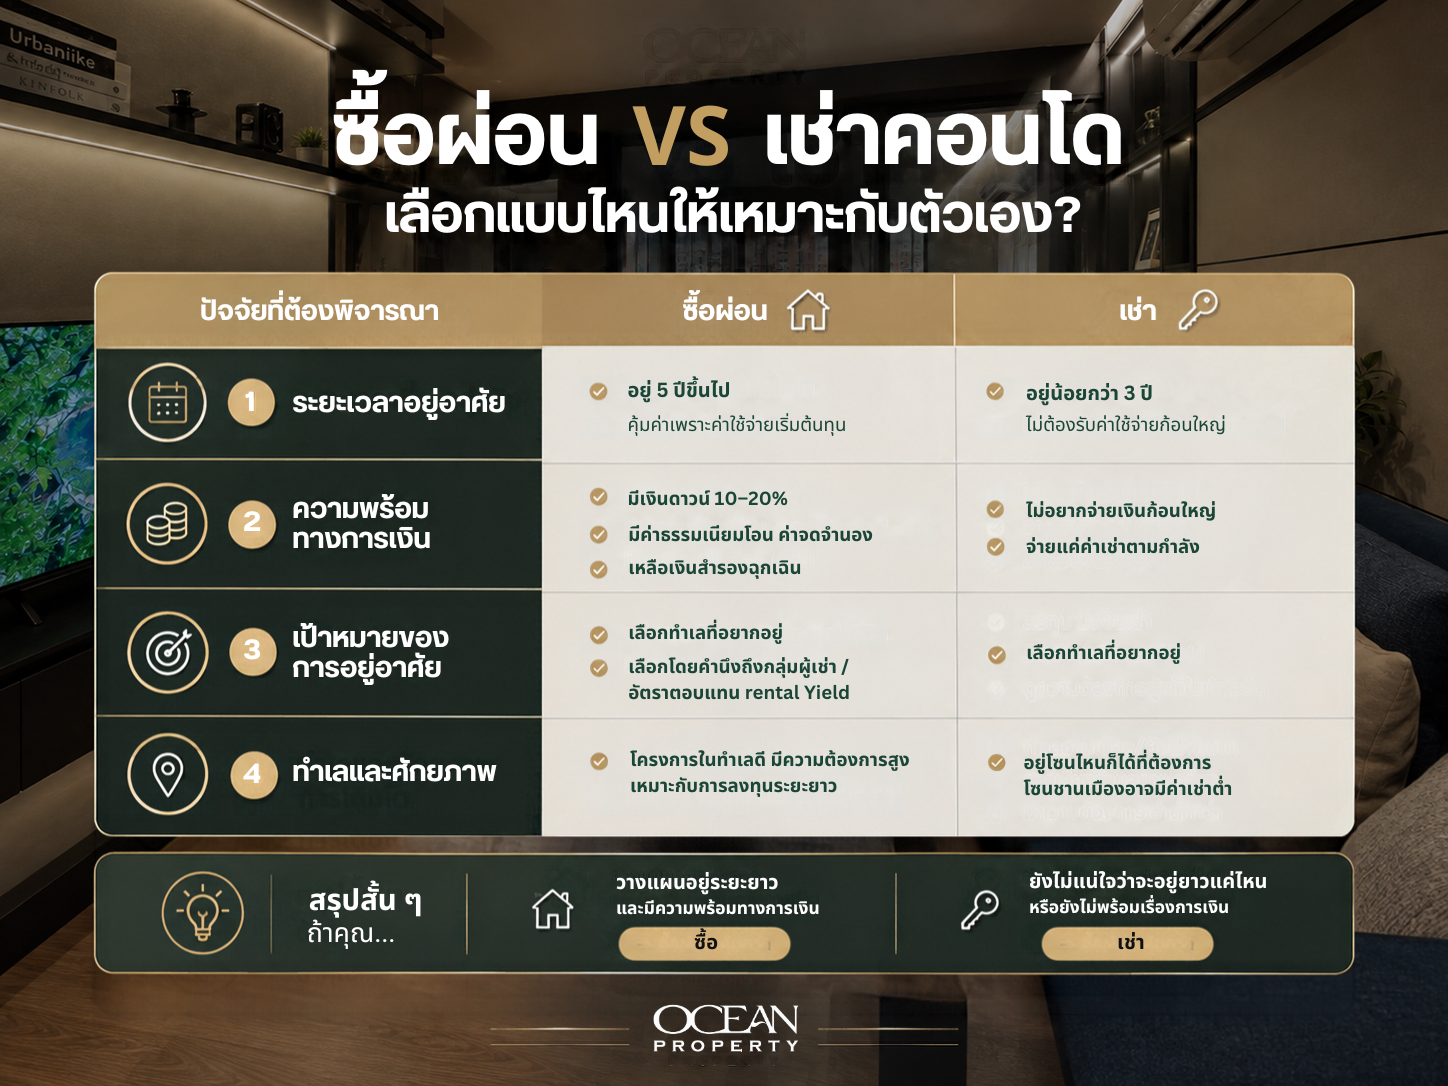
  • You become the owner of the asset. Each instalment pays down the principal, building long-term wealth—unlike rent, which is gone the moment you pay it, with nothing to show for it.
  • Potential for capital gains. If you choose a Khon Kaen location with strong growth potential, condo values tend to rise over time, and you can also generate rental income along the way.
  • Tax benefits. Mortgage interest on a home loan can be deducted from personal income tax, up to a maximum of THB 100,000 per year.
  • Full freedom to decorate. As the owner, you can build in fixtures or renovate the unit however you like, without needing anyone’s permission.

What Are the Drawbacks of Buying a Condo on a Mortgage?

  • A long-term commitment. Bank loan terms typically run 20–30 years. If your income runs into trouble down the line, it could affect your credit and financial liquidity.
  • Hidden costs to prepare for. Beyond the down payment, you’ll also need to budget for transfer fees, mortgage registration fees, sinking fund contributions, annual common area fees, insurance, and land and building tax.
  • Lower liquidity. If you need to convert the property back into cash, reselling takes considerable time and effort.

Who Is Buying on a Mortgage Best Suited For?

  • Those planning to stay in the location long-term, 5–8 years or more
  • Those with savings for the down payment, transfer costs, and an emergency reserve ready to go
  • Those with stable income who want to build an asset of their own
  • Those interested in Khon Kaen real estate investment to generate long-term rental income
     

Should You Rent a Condo for Now?

What Are the Benefits of Renting a Condo?

  • Highly flexible. Great for those who change jobs often, move locations frequently, or aren’t sure how long they’ll stay in one place—you can move out as soon as your lease ends.
  • Low upfront cost. No need for a large down payment—just a deposit and advance rent to move in.
  • No major repair responsibilities. If the structure or major fixtures break down, the landlord is responsible.
  • Frees up capital. Money you would have spent on a down payment can be invested elsewhere for potentially higher returns.

What Are the Drawbacks of Renting a Condo?

  • Rent doesn’t build an asset. You pay every month without gaining any ownership—the longer you rent, the more you spend with nothing to show for it.
  • Risk of rent increases. Landlords can raise the rent when renewing the lease, making long-term budgeting harder.
  • Limited freedom to decorate. You can’t renovate or change the unit as you wish—you’re stuck with the condition the landlord sets.

Who Is Renting Best Suited For?

  • Those planning to live somewhere for less than 3 years
  • Those who don’t yet have a large down payment, or want to preserve liquidity for now
  • Those who want to keep a flexible lifestyle, with a possibility of changing jobs or cities in the future
     

What to Consider: Buying vs Renting a Condo

What to consider: buying vs renting a condo

Before deciding, take a moment to assess yourself across these 4 areas:

1. How Long You’ll Actually Stay

If you plan to live in the location for less than 3 years, renting is usually the better value, since buying costs (down payment, transfer, mortgage registration) won’t yet have paid for themselves. If you plan to stay 5 years or more, buying starts to become more worthwhile.

2. Your Financial Readiness

Check whether you have enough for a down payment (typically 10–20% of the condo price), plus transfer and mortgage registration fees of around 1–3%, and still have an emergency fund covering at least 3–6 months of expenses. If you’re not quite there yet, renting while you continue saving may be the better move.

3. Your Purpose for Living There

Are you buying to live in, or to invest? If it’s for your own living, prioritise everyday happiness and a convenient location. If it’s for rental condo investment, analyse the rental yield and tenant demand in that location as well.

4. Location and Growth Potential

Location is the one factor you can’t change after buying. A condo near a university, hospital, or business district usually sees both strong rental demand and future capital gain potential, while an undeveloped suburban location may carry more liquidity risk.
 

Ocean Oasis Khon Kaen: The Answer for Those Ready to Buy

If you’ve decided you’re ready to buy a Khon Kaen condo on a mortgage that works for both living and Khon Kaen condo investment, Ocean Oasis Khon Kaen is the strongest option right now. Starting at just THB 1.59 million, it offers excellent value among Khon Kaen condo prices because:

  • A great location that covers every need. Situated on the Friendship Highway, it’s a condo near Khon Kaen University at just 800 metres away, 1.2 km from Bangkok Hospital Khon Kaen, and 2 km from Central Plaza Khon Kaen—convenient for living and backed by strong tenant demand if you choose to rent it out.
  • Fully loaded common facilities. No need to worry about quality of life, with a 25-metre Half-Olympic saltwater swimming pool, a fitness centre, a steam room, a co-working space, a sky bridge, a rooftop sky playground, and green space throughout the project.
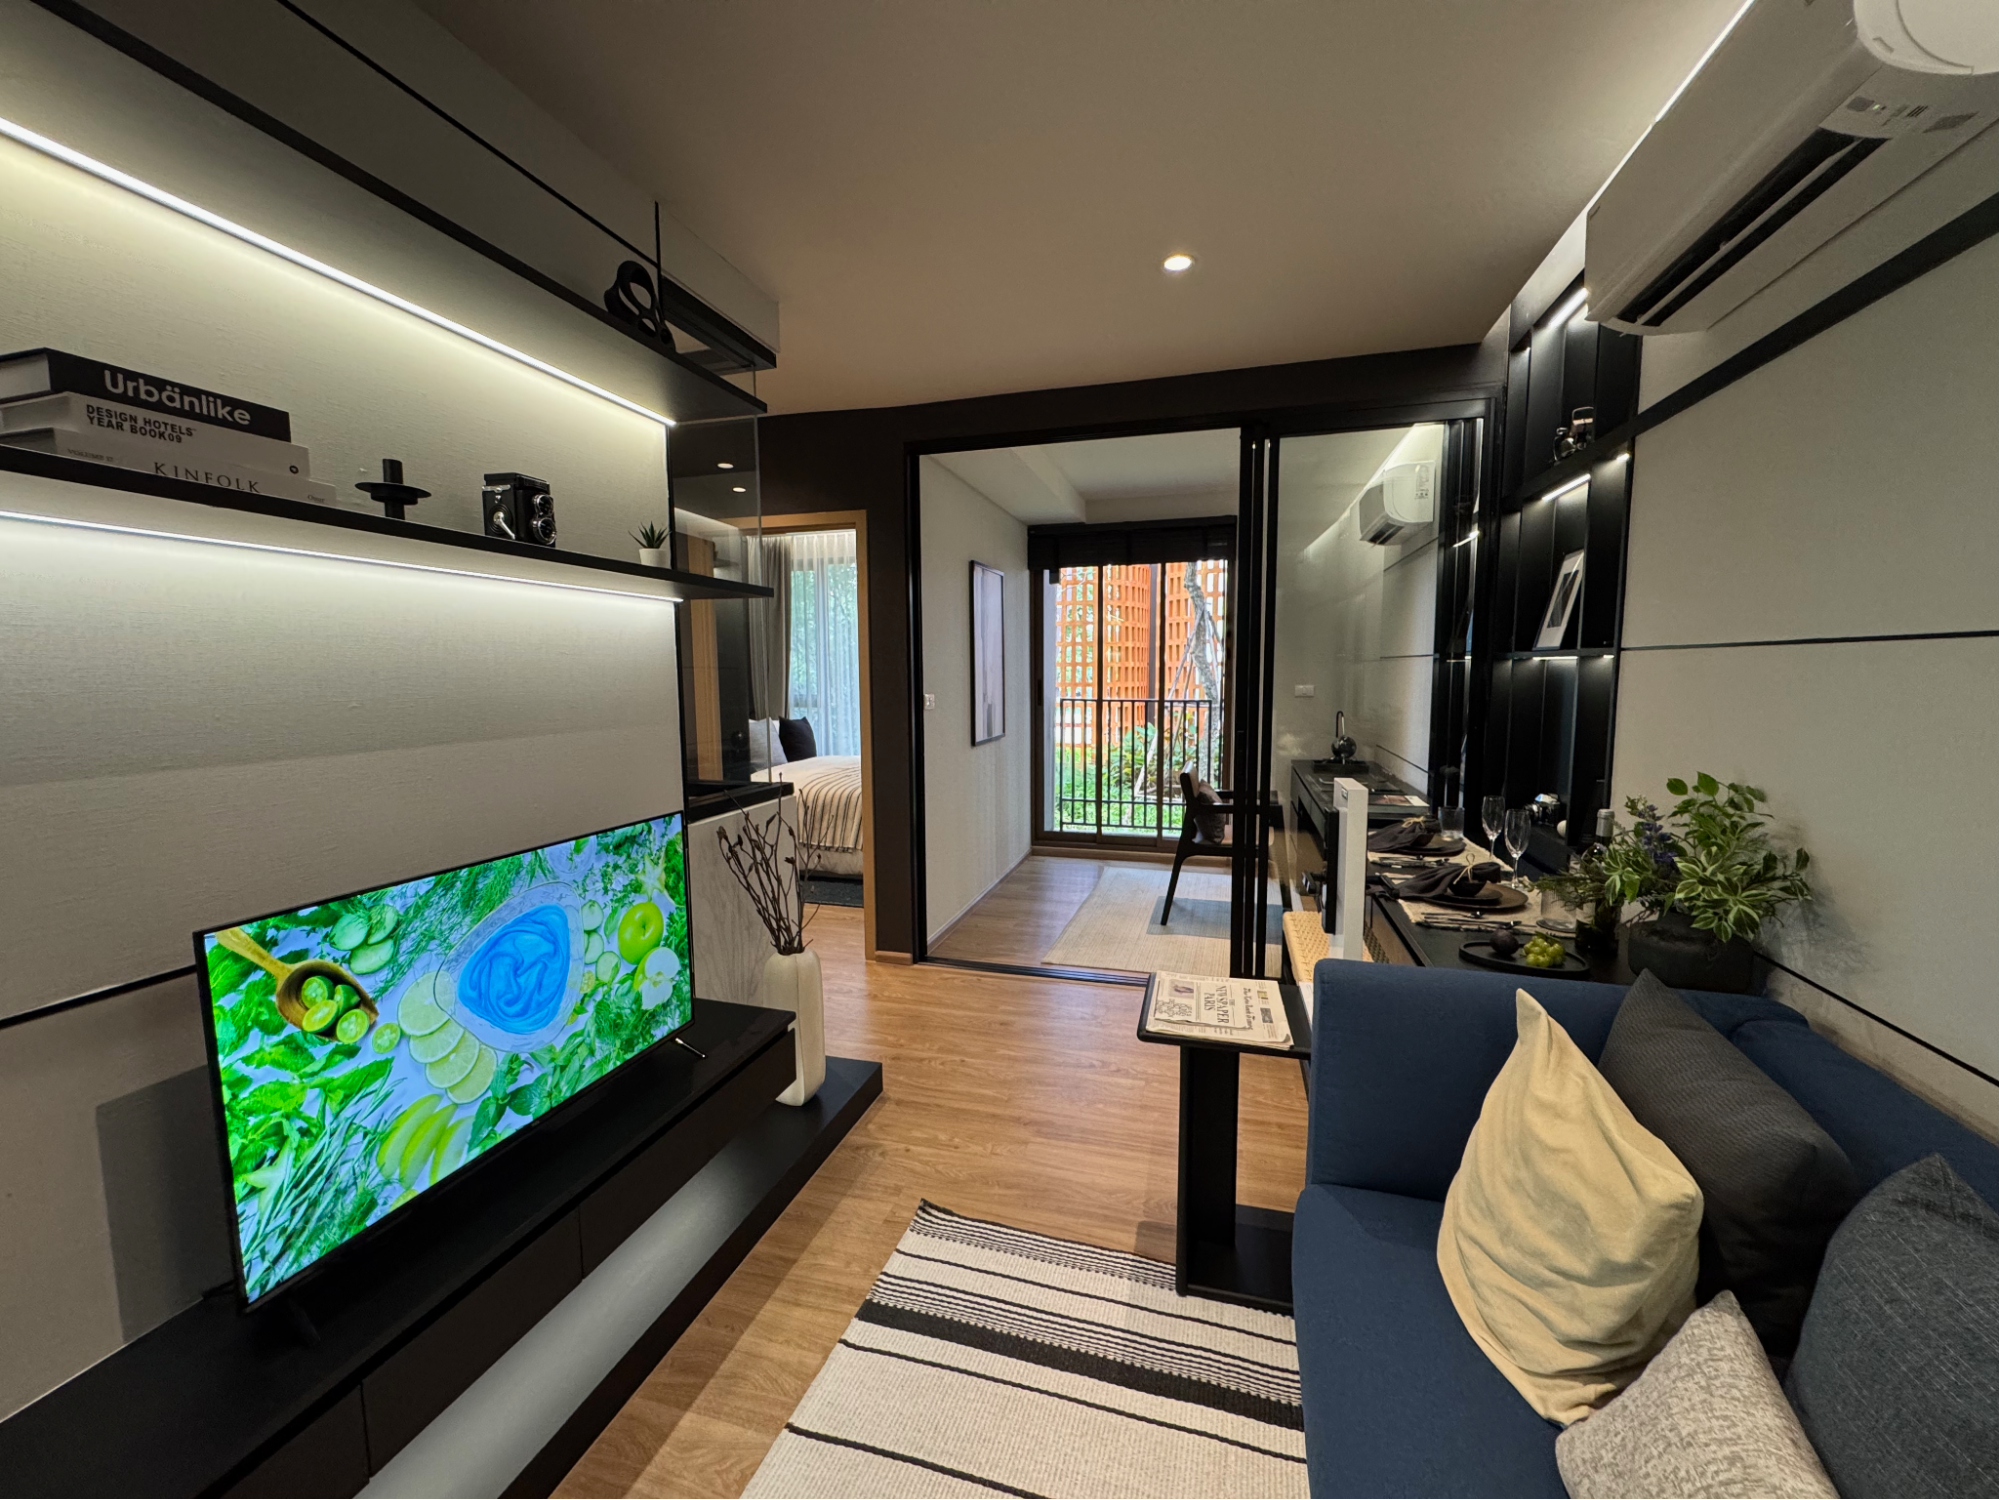
  • Units designed for real everyday living. The kitchen connects to the balcony for good ventilation without disturbing the rest of the unit. Choose from 5 room types, from Studio to 2 Bedroom, sized 23–47 sq.m., to fit your budget and lifestyle.
  • Guaranteed parking. No more competing for a spot, with a Smart Parking System and 24-hour security featuring facial recognition and CCTV.

For more project details or to arrange a show unit visit, please contact:

  • Tel: 02-038-5011
  • Facebook Page: https://www.facebook.com/OceanProperty
  • Email: info@oceanproperty.co.th
  • Sales Office Location: https://maps.app.goo.gl/Wt3kdeQko4UdaQ4b7
     

FAQs

Q: Is buying a condo on a mortgage a good idea for someone just starting their career?
A: Buying on a mortgage suits those starting their career with stable income who plan to settle in the location, since every instalment builds ownership. But if you’re still unsure about your job or where you’ll live, renting while saving for a down payment may be the better choice.

Q: Should I rent a condo for now, or buy right away?
A: If you plan to live somewhere for less than 3 years, or don’t yet have a down payment ready, renting for now is a reasonable choice, since it has lower upfront costs and keeps you flexible to move. But if you’re financially ready with a clear long-term plan, buying on a mortgage will likely be better value.

Q: Is buying a condo to rent out worth it in 2026?
A: It can be worthwhile if you choose a location with consistently strong rental demand, such as areas near a university or hospital. Condos in Khon Kaen can generate a rental yield of around 5–8% per year, which is an attractive figure compared to other forms of saving.

Q: How do the costs of buying vs renting a condo compare?
A: Renting has lower upfront costs—just a deposit and advance rent. Buying on a mortgage requires a down payment, transfer fees, mortgage registration fees, and annual common area fees. That said, money spent on a mortgage builds an asset, while rent is gone the moment you pay it, with no ownership gained.

Q: Is it a good idea to buy a condo if I’m not sure how long I’ll stay?
If you’re not sure how long you’ll be living somewhere, it’s better to rent for now. Buying and reselling a condo in the short term usually isn’t worth it, since transfer fees and other hidden costs won’t have been recovered. It’s best to be confident you’ll stay at least 5 years before deciding to buy.
  • Latest Article
    • Living Lifestyle
      Best Neighborhoods to Live in Khon Kaen: How to Choose the Right One
    • Living Lifestyle
      15 Must-Visit Temples in Khon Kaen: Shrines, Merit-Making & Mutelu Spots
    • Living Update
      Studio vs. 1-Bedroom: What's the Difference and Which Should You Choose?
    • Living Update
      Buying vs. Renting a Condo: Which Should You Choose?
  • Relate Article
    • Living Update
      Highlighting 9 Profitable Businesses for Commercial Buildings in Prime Locations in Phuket
    • Living Update
      What Is a Sustainable Condo? Eco-Friendly Living
    • Living Update
      Investing in Khon Kaen Condos: Rent, Locations & Yield
    • Living Update
      Ocean Town, Muang–Ratsada Phuket, Joins Government Housing Transfer & Mortgage Fee Reduction Program – Now Only 0.01%, Saving Buyers Tens of Thousands of Baht